Global market brief · 2026-08-04

Oil relief lifted U.S. stocks, but Asia chips kept de-crowding.

U.S. indexes rallied as oil fell, yields eased and megacap tech recovered. Asia did not fully follow: Taiwan, Korea and Japan weakened, TSMC fell near 1.9%, and TraderXYZ volume rose mainly with memory-chain selling pressure rather than a clean bullish breakout.

Updated: 2026-08-04Theme: Oil relief + hyperscaler monetization + TSMC weakness + memory de-crowdingCoverage: SPX, NDX, MSFT, META, AMZN, NVDA, AMD, AAPL, TSMC, MU, SKHX, DRAM, SNDK, Fed, Brent, TraderXYZ, Hyperliquid
Main read

The AI infrastructure cycle is intact, but semiconductor beta is fading.

The market is rotating from “all AI hardware wins” toward companies that can prove revenue, profit and free-cash-flow returns. Hyperscalers were rewarded, while semiconductors still have fundamental support but face lower valuation elasticity and higher volatility.
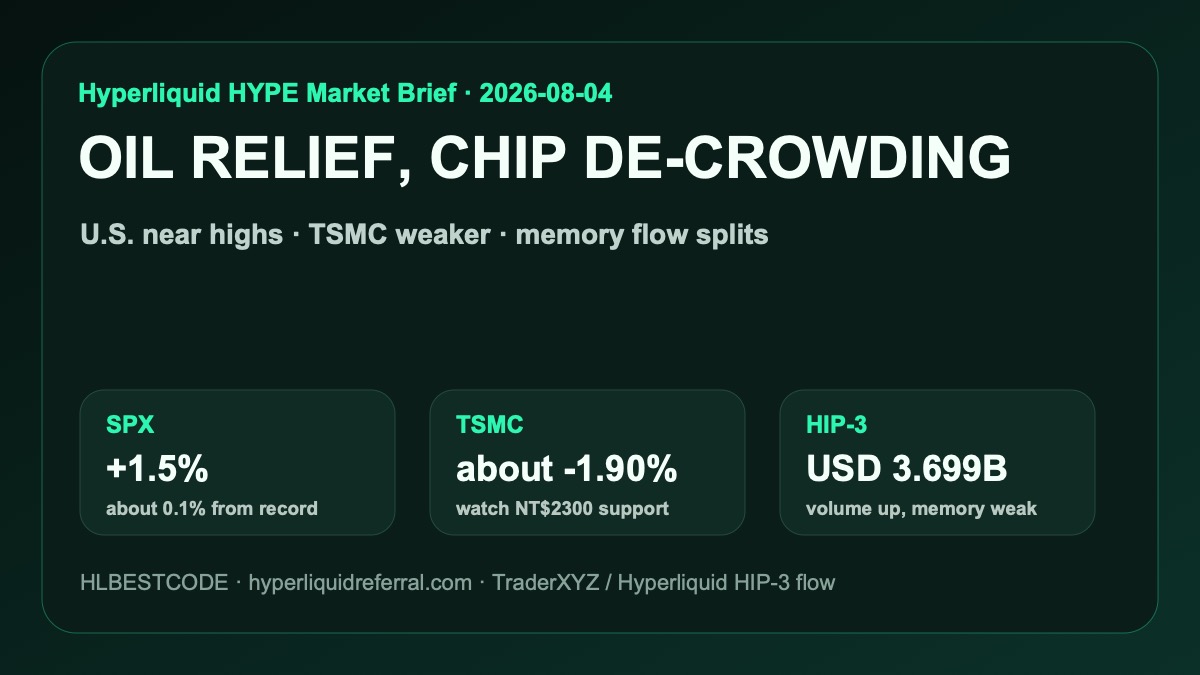
Hyperliquid HYPE Market Brief 2026-08-04 | Oil relief, hyperscaler strength and chip de-crowding
1. U.S. risk appetite is strong, but macro-sensitiveS&P 500 rose 1.5% to 7600.50, Dow set a closing high, and Nasdaq rose 2.1%. The rally was helped by Brent falling 4.7%, but oil was already rebounding around midday Asia.
2. Asia did not fully follow Wall StreetTaiwan Weighted was down about 0.37%, TSMC about -1.90%, KOSPI about -1.18% and Nikkei about -0.60%. Asia chip positioning is still being reset after last week’s violent moves.
3. TraderXYZ volume rose with disagreement, not pure risk-onTop-ten HIP-3 24h notional rose to about USD 3.699B, but SKHX, MU, DRAM and SKHY fell while SNDK rose. This looks like memory-chain position adjustment.
4. Hyperscaler monetization is becoming the main testMicrosoft, Amazon and Alphabet-type cloud platforms are favored when AI spending turns into revenue and profit. Chip suppliers still benefit, but clients’ free cash flow now matters more.

Key Data

2026-08-04 12:20 Beijing time snapshot; Taiwan data are midday references and TraderXYZ uses rolling 24h HIP-3 flow.

Macro and policy

U.S. stocks were lifted by lower oil, easing long-end pressure and megacap repair. Yet 10Y yields remain near 4.7%, and the Fed is still operating with inflation above target. Strong jobs data would keep tightening risk alive; weak jobs with high inflation would raise growth concerns.

U.S. market and companies

S&P 500 closed at 7600.50, +1.5%, about 0.1% below its record close. Dow closed at 53178.41, +1.3%, a new closing high; Nasdaq +2.1%. Microsoft +4.9%, Meta +6.0%, Amazon +4.6%, Nvidia +2.9%, AMD +1.8%, Apple -1.8%, SOXX +0.6%.

Asia and TSMC

Taiwan Weighted was near 43228, -0.37%, while TSMC traded near NT$2325, about -1.90%. TSMC fundamentals remain strong, but after a break below NT$2350 the short-term focus is NT$2300 support and whether foreign flows stabilize.

AI capex and supply chain

Amazon raised 2026 capex to USD 220B and AWS growth accelerated to 37%, supporting the idea that compute demand has not peaked. Goldman Sachs AM points to enterprise token consumption and optical interconnects; Morgan Stanley frames AI as compute, power, cooling and financing buildout.

TraderXYZ HIP-3

Top-ten 24h notional volume was about USD 3.699B, up roughly 148% from yesterday. The structure is mixed: SP500 and XYZ100 rose, energy rebounded, while SKHX, MU, DRAM and SKHY fell. The clean read is decent index risk appetite but continued chip de-crowding.

Risk note

Perpetual contracts use leverage and can turn over repeatedly. They help read crowding and direction, but should be cross-checked with cash equities, ETFs, options and company fundamentals.

Sources: TWSE realtime quotes · AP: August 3 U.S. markets · Reuters / Investing.com: Morgan Stanley on hyperscalers vs chipmakers · Goldman Sachs: AI adoption and inference demand · Goldman Sachs: Jim Covello on AI payback · Morgan Stanley: AI buildout, monetization and financing · New York Fed: August 2026 economic calendar · Hyperliquid public info API

For a focused Hyperliquid ecosystem view, see the HYPE market brief hub.