Demand is intact, but capital returns now matter more than slogans.
The baseline remains constructive for AI infrastructure: cloud demand, HBM, advanced packaging, optics, power and data-center construction are still expanding. The short-term risk is different: high valuation, crowded ownership, higher rates and weaker capex payback can overwhelm good demand.
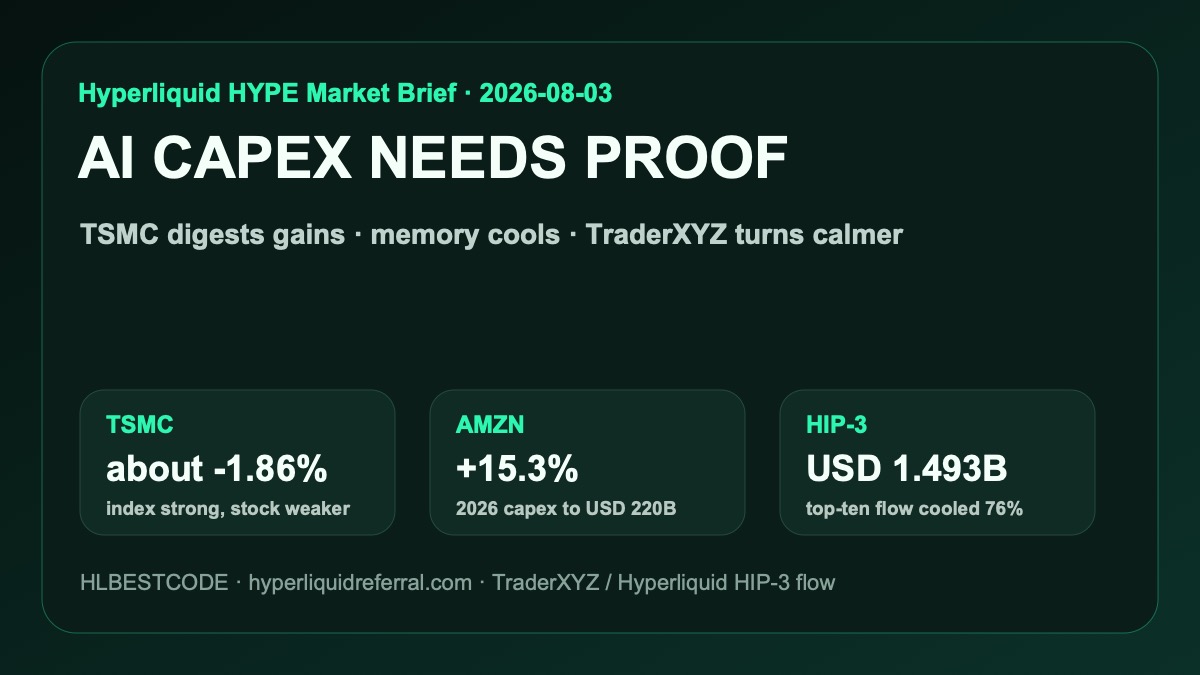
1. AI capex has not peakedAmazon lifted 2026 capex from USD 200B to USD 220B and said demand still exceeds supply. Morgan Stanley still sees a multi-year data-center buildout.
2. Monetization is now the gatekeeperMicrosoft was rewarded because AI demand converts into Azure revenue and profit. Apple fell on weaker guidance, and Meta was punished earlier when spending pressure hit profits.
3. Taiwan is splitting internallyTaiwan Weighted was up around 0.56% near midday, while TSMC fell about 1.86% after last Friday’s surge. This looks more like rotation and digestion than a full AI unwind.
4. Memory is still tight, but the chase cooledMU, SNDK and DRAM remain active on TraderXYZ, but top-ten HIP-3 notional volume fell roughly 76% versus the comparable Friday window. Less heat is not the same as broken fundamentals.