Global market brief · 2026-07-28

Asia chips deleverage as CXMT resets memory risk.

Korea and Taiwan semiconductor assets sold off sharply while TSMC outperformed the broader Taiwan market. CXMT raised DRAM competition fears, but tonight the key confirmation still comes from U.S. cash trading, Fed pricing and Microsoft/Meta AI capex returns.

Updated: 2026-07-28Theme: Asia chip deleveraging + CXMT memory shock + TSMC resilience + Fed and megacap earningsCoverage: TSMC, MU, SKHX, Samsung, CXMT, DRAM, NVDA, AMD, Microsoft, Meta, Fed, TraderXYZ
Main read

Direction is credible; exact perp moves are not.

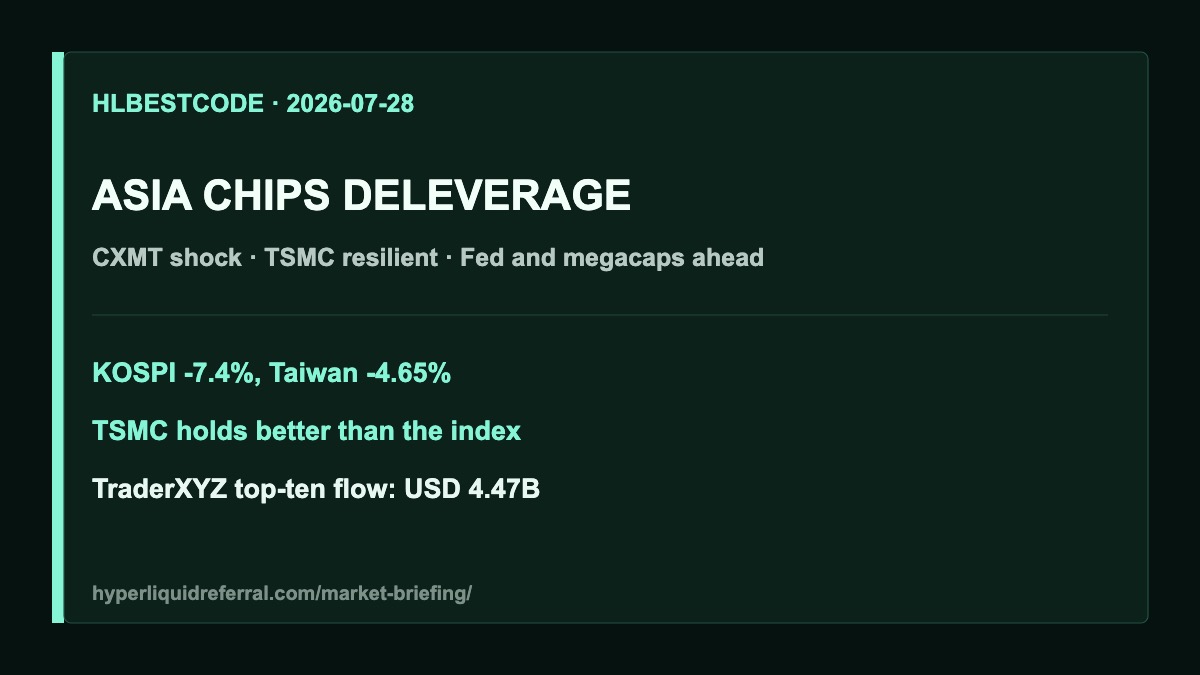
TraderXYZ top-ten notional flow jumped to about USD 4.47B, up roughly 202% from yesterday, and aligned with Korea, Taiwan and Japan spot weakness. That makes the risk-off direction useful, but leveraged perpetuals still exaggerate exact opening levels.
Hyperliquid HYPE Market Brief 2026-07-28 | Asia chip deleveraging and CXMT memory shock
1. Asia chip deleveraging is regionalKOSPI fell about 7.4%, Samsung and SK Hynix dropped around 9-10%, Taiwan Weighted lost about 4.65%, and Japan also weakened intraday. This is no longer a single-stock move.
2. TSMC is holding better than the tapeTSMC closed near NT$2280, down about 2.98%, versus Taiwan Weighted -4.65%. Its moat is advanced logic, advanced packaging and customer ecosystem, not commodity DRAM.
3. CXMT matters most for memory multiplesCXMT funding and IPO momentum pressure generic DRAM expectations, but HBM, yield, thermal design, packaging and international customer qualification remain separate hurdles.
4. Fed and megacap earnings set the next testMicrosoft and Meta must show AI revenue and operating cash flow can justify capex. A hawkish Fed pause could add another pressure point for high-duration tech.

Key Data

Taiwan and Korea data are July 28 close or near-close; TraderXYZ is intraday around 14:20 Beijing time; U.S. data use July 27 close.

Taiwan and TSMC

Taiwan Weighted closed near 41,603.36, -4.65%. TSMC closed at NT$2280, -2.98%, outperforming the index by about 1.67 percentage points.

Korea and memory

KOSPI fell about 7.41% to 6,253.81. Samsung fell about 9.15% and SK Hynix about 10%, with index concentration and program limits amplifying stress.

U.S. close

S&P 500 +0.02%, Dow +0.51%, Nasdaq -0.18%. SOX fell about 2.2%; NVDA -5.0%, AMD -5.2%, MU -2.2%, TSM ADR -1.0%.

TraderXYZ

Top-ten notional volume was about USD 4.47B, up around 202% from yesterday. SKHX, SNDK, MU, SKHY and DRAM led the downside flow.

Macro and Fed

Oil and yields eased, but semis still fell. That means the market is pricing valuation, competition and AI capex return risk, not only inflation.

Strategy frame

Control leverage first. A cleaner reversal needs KOSPI stabilization, TSMC back above NT$2350, shrinking TraderXYZ downside volume and Microsoft/Meta proof of AI cash returns.

Sources: AP: July 27 stocks, oil and bonds · Reuters: Wall Street, SOX and Fed pricing · AP: Korea, Taiwan and Asia markets · Reuters: KOSPI, Samsung, SK Hynix and CXMT impact · AP: CXMT listing · TSMC official Q2 2026 results · Goldman Sachs: U.S. midyear and Fed outlook · J.P. Morgan: Fed policy outlook · Apollo: market volatility week · S&P Global: Microsoft and Meta earnings previews · Microsoft investor relations · TraderXYZ

For a focused Hyperliquid ecosystem view, see the HYPE market brief hub.